


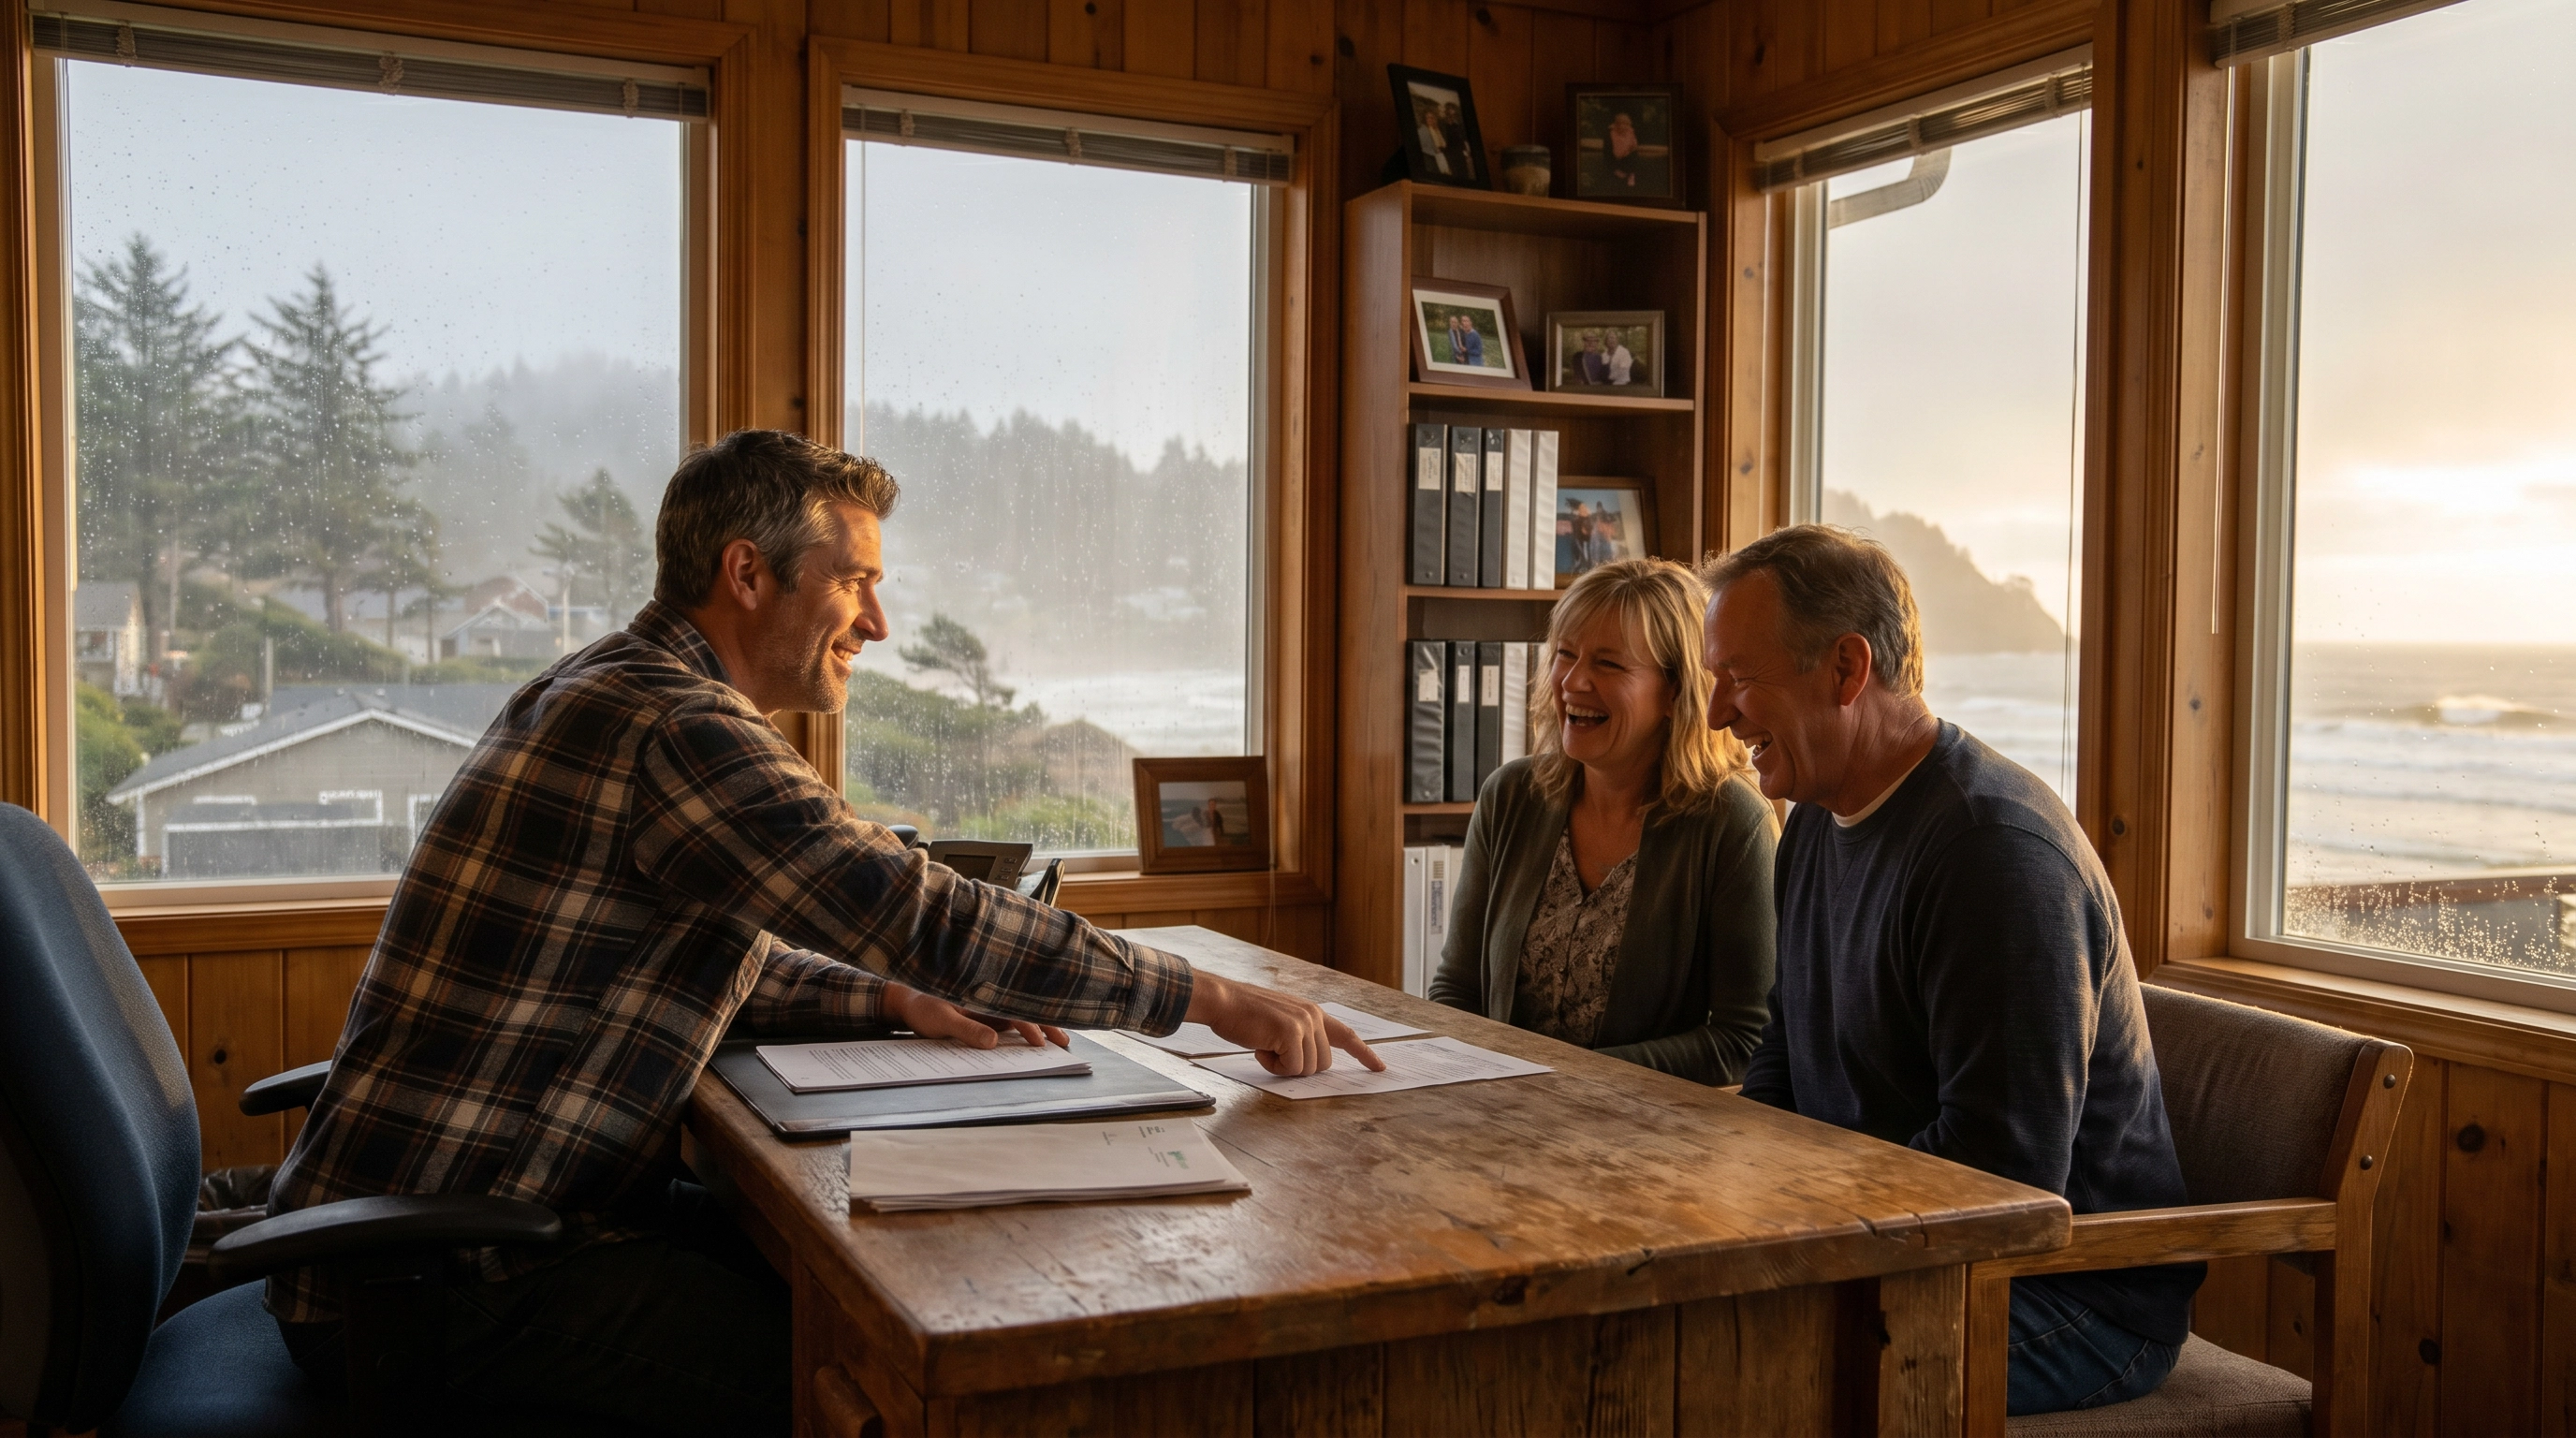

You've seen the ads. Fifteen minutes could save you fifteen percent. Bundle and save. Get your quote in seconds. The insurance industry has spent billions of dollars convincing consumers that buying insurance is a simple transaction — a commodity you can shop for like a flight or a hotel room. But here on the Oregon Coast, where a single wildfire season can reshape the entire insurance market, where a fishing boat, a vacation rental, and a small business can all share the same owner, and where the difference between a covered claim and a denied one often comes down to a single policy endorsement, the algorithm doesn't know your name. And that matters more than most people realize.
Talk to a Real Agent — Not a Chatbot
Gerald Ross Agency represents over 40 carriers. We shop your coverage, explain your options, and stay with you through every claim. No call centers, no algorithms.
What "Independent" Actually Means
The term "independent insurance agent" gets thrown around a lot, but its meaning is specific and important. An independent agent is not employed by any single insurance company. Instead, they hold contracts with multiple carriers — sometimes dozens — and can place your coverage with whichever company offers the best combination of price, coverage, and claims service for your specific situation.
This is fundamentally different from a captive agent, who works exclusively for one company (think State Farm, Allstate, or Farmers). A captive agent can only offer you their employer's products. If their carrier doesn't write your type of property, doesn't cover your business class, or has pulled out of your zip code after wildfire losses, they have nothing to offer you. An independent agent, by contrast, can move to the next carrier on their list.
According to the Independent Insurance Agents & Brokers of America, independent agents write approximately 61.5% of all property and casualty insurance in the United States — including 85% of commercial lines. The market has spoken: when the stakes are real, people choose agents who work for them, not for a single carrier.
What Online Quote Tools Can't Do
Online insurance platforms are genuinely useful for simple, standardized risks. A young renter in a city apartment with a ten-year-old Honda Civic and no unusual exposures can probably get a fine policy online in fifteen minutes. But most people's lives — and especially most Oregon Coast lives — are not that simple.
Here is what the algorithm cannot do for you:
- Identify coverage gaps before a claim. Online tools ask you a series of questions and build a policy from your answers. But they can't ask the follow-up questions a trained agent would ask — questions like "Do you rent out your property on Airbnb?" or "Do you have a trampoline?" or "Does your home-based business have clients who visit?" Each of those answers changes your coverage needs significantly, and the algorithm won't flag the gap until after a loss.
- Access specialty and regional carriers. Many of the best carriers for Oregon Coast properties — those with the most competitive rates for coastal homes, fishing vessels, vacation rentals, and small commercial operations — don't sell directly to consumers. They only work through licensed independent agents. If you're buying online, you're not seeing the full market.
- Navigate a hard market. When carriers pull out of a market (as many have done in wildfire-exposed areas of Oregon and Northern California), online platforms simply return "no quotes available." An independent agent knows which carriers are still writing, which are offering surplus lines coverage, and how to structure your application to maximize your options.
- Advocate for you during a claim. This is the biggest one. When you have a claim, an online portal gives you a claim number and a phone tree. An independent agent calls the adjuster directly, documents your loss, pushes back on underpayments, and escalates when needed. That advocacy is worth far more than any discount.
- Understand your local risk environment. A local agent knows that certain zip codes on the Oregon Coast have wind-driven rain exclusions. They know which carriers are tightening coastal property underwriting. They know the difference between a Curry County wildfire exposure and a Lincoln County coastal flood exposure. That local knowledge is not in any algorithm.
Is Your Current Coverage Leaving Gaps?
A free policy review from Gerald Ross Agency takes 20 minutes and often uncovers coverage gaps that could cost you thousands in a claim. No obligation, no pressure.
The Hard Market Reality
The insurance market has hardened significantly since 2020. Wildfire losses in Oregon and California, back-to-back severe storm seasons, and rising reinsurance costs have pushed carriers to tighten underwriting, raise rates, and in some cases exit markets entirely. Homeowners in parts of Southern Oregon and Northern California have seen non-renewals from carriers they've been with for decades.
In this environment, the value of an independent agent becomes even more pronounced. When your carrier sends a non-renewal notice, an independent agent can immediately begin shopping replacement coverage across their entire carrier portfolio. They know which carriers are still writing in your area, which require specific mitigation measures (defensible space, Class A roofing, ember-resistant vents), and how to present your property in the most favorable light to underwriters.
An online quote tool, by contrast, will simply tell you that no quotes are available. A captive agent will tell you their company can't help you. An independent agent will find a solution — or tell you honestly what your options are, including the Oregon FAIR Plan if necessary.
The Claims Advocacy Difference
Ask anyone who has filed a significant insurance claim what they wish they had known beforehand, and a common answer is: "I wish I had someone in my corner." Insurance companies have teams of adjusters, attorneys, and claims specialists whose job is to evaluate claims accurately — but whose incentives are not perfectly aligned with paying you the maximum amount as quickly as possible.
An independent agent who knows your policy, knows your property, and has a relationship with the carrier's claims department is an enormous asset when you're dealing with a fire loss, a flood, a liability claim, or a business interruption. They can:
- Help you document your loss thoroughly before the adjuster arrives
- Identify all coverages that may apply to your claim (many policyholders leave money on the table by not knowing about additional living expense coverage, ordinance or law coverage, or equipment breakdown coverage)
- Push back on low settlement offers with policy language and precedent
- Escalate to a supervisor or file a complaint with the Oregon Insurance Division if needed
- Connect you with a public adjuster if the claim is large and complex
None of this is available from an 800 number or an online portal. It comes from a relationship — the kind that only exists when a real person knows your name, your property, and your situation.
What to Look for in an Independent Agent
Not all independent agents are equal. Here are the qualities that distinguish a genuinely valuable agent from one who is simply processing transactions:
| Quality | Why It Matters |
|---|---|
| Multiple carrier appointments | More options means better rates and coverage for your specific situation |
| Local market knowledge | Understands regional risks — wildfire, coastal flooding, wind, earthquake — and which carriers are writing |
| Commercial lines expertise | Can handle business, farm, marine, and specialty risks, not just personal lines |
| Claims advocacy track record | Has a history of going to bat for clients during claims, not just at renewal |
| Proactive communication | Reviews your coverage at renewal, flags changes in the market, and reaches out when your situation changes |
| Licensed in your state | Properly licensed in Oregon and/or California for your coverage needs |
Oregon Coast Insurance: Why Local Expertise Matters
The Oregon Coast presents a genuinely unique insurance environment. Coastal properties face wind-driven rain, saltwater corrosion, and storm surge risks that inland carriers don't fully understand. Vacation rental owners have a complex mix of personal, commercial, and liability exposures. Fishing and charter boat operators need marine coverage that most agents have never placed. Small businesses in coastal communities often have seasonal revenue patterns that affect business interruption calculations.
A local agent who has placed coverage for Brookings homeowners, Gold Beach vacation rentals, Coos Bay commercial fishermen, and Newport restaurant owners understands these nuances in a way that a national call center agent never will. They know which carriers have been reliable in Oregon claims, which have been slow to pay, and which have been quietly tightening their underwriting in coastal zip codes.
Gerald Ross Agency has been serving the Oregon Coast and Southern Oregon since the agency's founding. We represent over 40 carriers and place coverage for personal lines, commercial businesses, marine and fishing operations, vacation rentals, and agricultural operations across the region. Our clients range from Brookings retirees protecting a lifetime of savings to Grants Pass contractors managing complex commercial liability to Coos Bay seafood processors needing specialized marine coverage.
Related Coverage Areas
Whether you're a homeowner, business owner, or both, Gerald Ross Agency can help you build a comprehensive coverage program:
- Homeowners Insurance — including coastal and wildfire-exposed properties
- Commercial Property Insurance — for businesses of all sizes
- Commercial Umbrella Insurance — extra liability protection above your primary policies
- Marine Insurance — for fishing vessels, charter boats, and watercraft
- Tips to Keep Insurance Costs Down — practical strategies for Oregon businesses
- EV & E-Bike Insurance for Coastal Businesses — coverage for the electric economy
Frequently Asked Questions
What is the difference between an independent agent and a captive agent?▼
Is it cheaper to buy insurance directly online?▼
What does an independent insurance agent do during a claim?▼
How does an independent agent get paid?▼
Can an independent agent help if my carrier non-renews my policy?▼
Does Gerald Ross Agency serve areas outside Brookings?▼
How do I switch from my current carrier to Gerald Ross Agency?▼
Experience the Difference a Local Agent Makes
Gerald Ross Agency has been helping Oregon Coast and Southern Oregon residents and businesses navigate the insurance market for years. We represent over 40 carriers, we know the local risk environment, and we stay with you through every claim. Call us, email us, or request a quote online — and find out what it feels like to have a real person in your corner.


