


Oregon Coast & Southern Oregon
Fire Mitigation Guide
Defensible space, home hardening, and documentation strategies that reduce your wildfire risk and unlock better insurance options on the Oregon Coast.
Our Approach
Assess. Document. Unlock Better Coverage.
Fire mitigation only saves you money on insurance when it is properly documented. Here is how Gerald Ross Agency turns your improvements into insurance leverage.
Assess Your Property
We review your home's wildfire risk profile — vegetation, roof type, vents, decking, and proximity to wildland fuels. We identify which mitigation improvements will have the greatest impact on your insurance options and premium.
Document Your Improvements
We help you compile the documentation carriers require: photos, receipts, inspection reports, and third-party certifications like IBHS Wildfire Prepared Home. Proper documentation is the difference between a carrier credit and a declined application.
Unlock Better Coverage
With documented mitigation, we shop your property across 50+ carriers — including specialty markets that reward mitigation with lower premiums, broader terms, and higher limits. Many clients save 15–30% compared to undocumented properties.
Defensible Space
The Three Defensible Space Zones
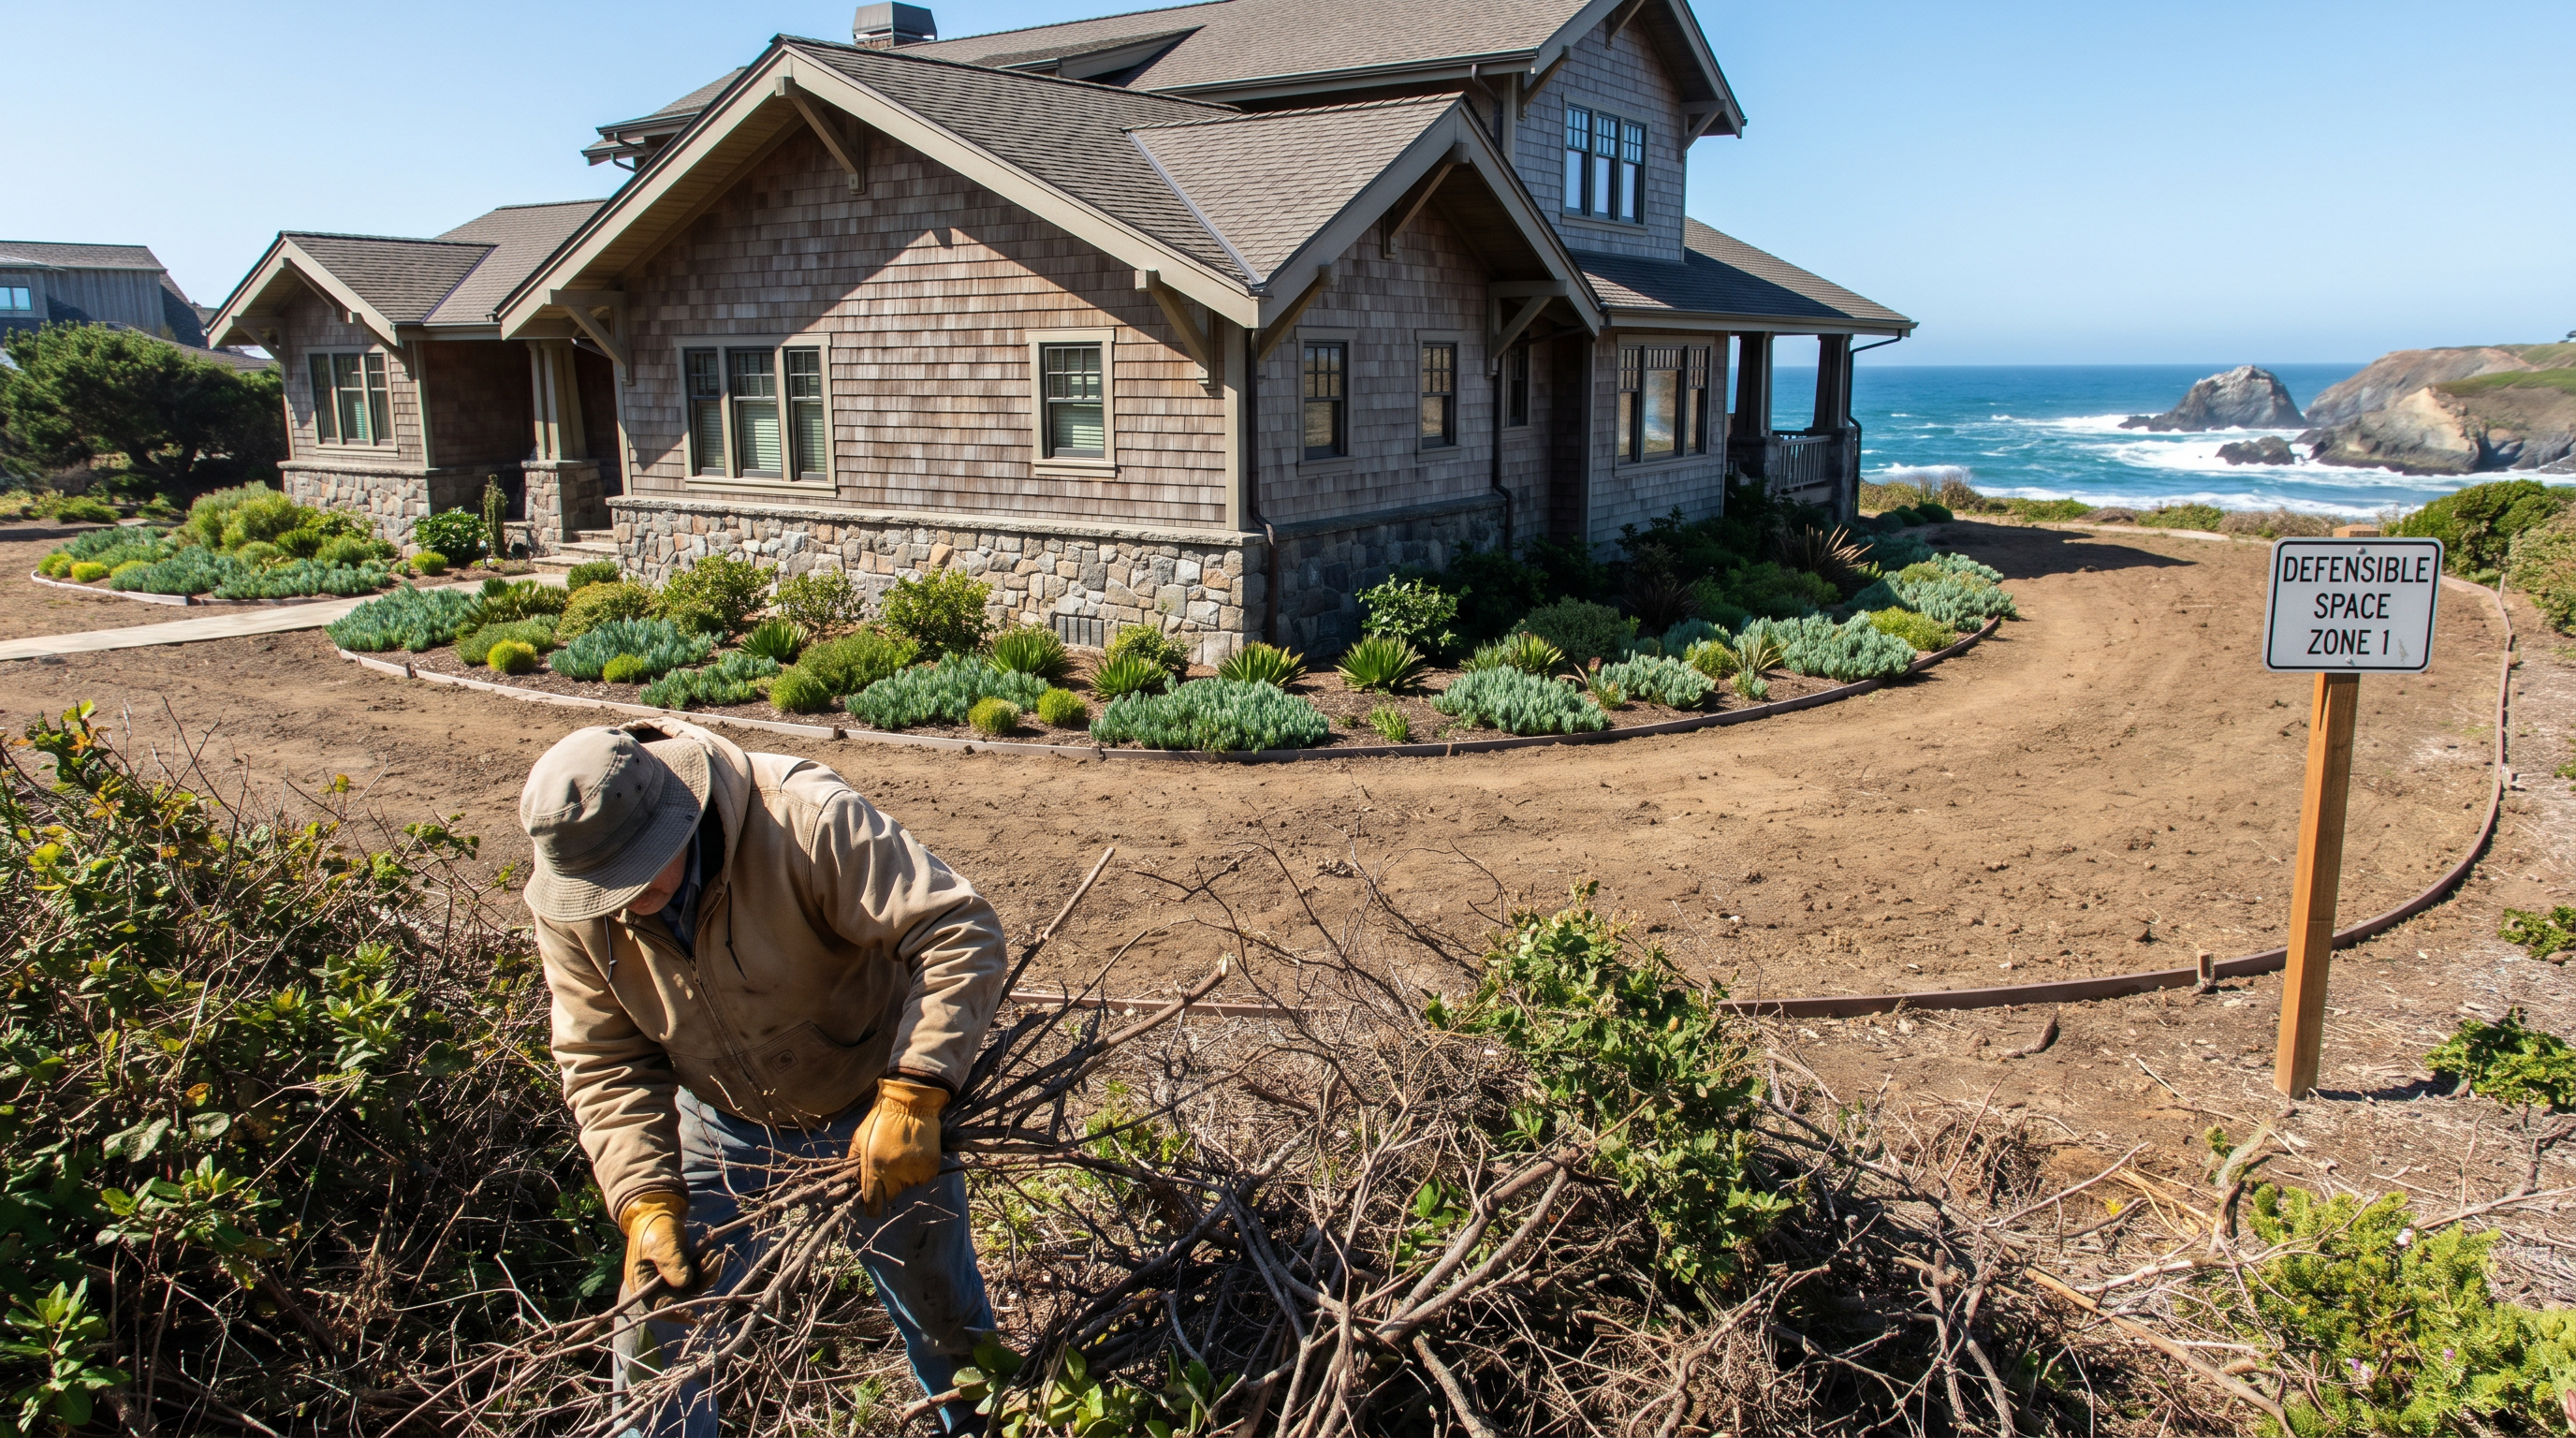
Oregon and California both use a three-zone defensible space model. Each zone has specific requirements that insurers look for when evaluating your property.
Zone 0 — Immediate (0–5 ft)
- ✓Remove all combustible materials from under decks and within 5 feet of the structure
- ✓Use non-combustible mulch (gravel, decomposed granite) instead of wood chips
- ✓Remove dead plant material, leaves, and debris from roof and gutters
- ✓Install ember-resistant vents (1/16-inch mesh or IBHS-rated)
- ✓Replace wood decking with composite or non-combustible materials
- ✓Ensure no wood piles, propane tanks, or combustibles are stored against the home
Zone 1 — Lean, Clean, and Green (5–30 ft)
- ✓Remove dead plants, grass, and weeds regularly
- ✓Space trees so canopies do not touch — minimum 10 ft between canopy edges
- ✓Prune tree branches to a height of 6–10 ft from the ground
- ✓Remove ladder fuels (shrubs under trees that allow fire to climb)
- ✓Keep grass mowed to 4 inches or less during fire season
- ✓Remove or relocate wood piles at least 30 ft from the structure
Zone 2 — Reduced Fuel (30–100 ft)
- ✓Cut or mow annual grasses when they turn brown
- ✓Remove highly flammable plants and shrubs (manzanita, juniper, gorse)
- ✓Create horizontal spacing between shrubs and trees
- ✓Remove dead plant material throughout the zone
- ✓Ensure emergency vehicles can access and turn around on your property
Home Hardening
Six Home Hardening Improvements That Matter for Insurance
Not all home hardening improvements are equal from an insurance standpoint. These six have the greatest impact on carrier eligibility and premium credits.
Class A Roofing
Metal, tile, or Class A asphalt shingles are the single most impactful home hardening improvement. Most carriers require Class A roofing for WUI properties. Replacement cost: $15,000–$40,000 depending on size.
Ember-Resistant Vents
Attic, foundation, and crawl space vents with 1/16-inch metal mesh or IBHS-rated ember-resistant covers prevent ember intrusion — the number one cause of home ignition in wildfires.
Non-Combustible Siding
Fiber cement, stucco, metal, or brick siding significantly reduces ignition risk. Replace wood or vinyl siding on at-risk elevations facing wildland fuels.
Composite or Metal Decking
Wood decks are a primary ignition point. Replacing with composite (Trex, TimberTech) or metal decking and using non-combustible fascia boards dramatically reduces risk.
Multi-Pane Windows and Tempered Glass
Single-pane windows can fail in radiant heat before flames arrive. Dual-pane or tempered glass windows significantly improve heat resistance.
Defensible Space Documentation
ODF (Oregon Department of Forestry) inspections and CAL FIRE assessments provide third-party documentation of your defensible space work — the format most carriers require for credits.
Ready to Turn Your Mitigation Into Insurance Savings?
Gerald Ross Agency helps Oregon Coast and Southern Oregon homeowners document their improvements and access specialty carriers that reward mitigation. Get a quote today.
Client Scenarios
How Mitigation Documentation Made the Difference
Real situations where proper mitigation documentation changed the outcome for Oregon Coast and Southern Oregon homeowners.
Oregon Coast — Curry County
"A Brookings homeowner was facing non-renewal after their carrier exited the county. Their home had a risk score of 74 and no documented mitigation."
After completing Zone 0 and Zone 1 work and obtaining an ODF inspection, Gerald Ross Agency placed them with a specialty carrier at a premium 14% below their previous policy.
Southern Oregon — Rogue Valley
"A Gold Beach homeowner had completed a new Class A metal roof, ember-resistant vents, and composite decking — but their carrier had not credited any of it at renewal."
We documented all improvements and re-shopped the policy. The homeowner saved 19% annually by switching to a specialty carrier that actively rewards mitigation documentation.
Northern California — Del Norte County
"A Crescent City homeowner was told by their standard agent that their property was uninsurable after their carrier exited the county."
After completing Zone 0 hardening and obtaining a CAL FIRE inspection, Gerald Ross Agency placed them through a surplus lines market at competitive rates.
Related Wildfire Resources
FAQ
Frequently Asked Questions
Does fire mitigation actually lower my insurance premium in Oregon?▼
What is the Oregon R327 building code for wildfire?▼
Does the Oregon Department of Forestry offer free defensible space inspections?▼
What is IBHS Wildfire Prepared Home certification?▼
How long does it take to complete defensible space work?▼
Can fire mitigation help me get coverage after a non-renewal?▼
Get in Touch
Ready to protect what matters most? Contact us today for a no-obligation insurance review. Our experienced agents are here to help you find the right coverage for your needs.


